Electronic invoicing in the UAE is moving from policy to implementation. Although many organizations will first approach it as a tax and technology programme, it also raises practical questions for Procurement, Accounts Payable, supplier management, Finance, and ERP teams.
“If a supplier already submits invoices through a customer portal for three-way matching, will the same invoice now have to be submitted again through the UAE e-invoicing system?”
The answer is not a simple yes or no. The UAE model is not merely a government portal into which suppliers upload invoices. It is based on structured electronic invoice data, the Peppol framework, and Ministry of Finance-accredited service providers. Whether duplicate submission is required will depend largely on how each buyer designs and integrates its future invoice-receipt process.
1. What Is UAE E-Invoicing?
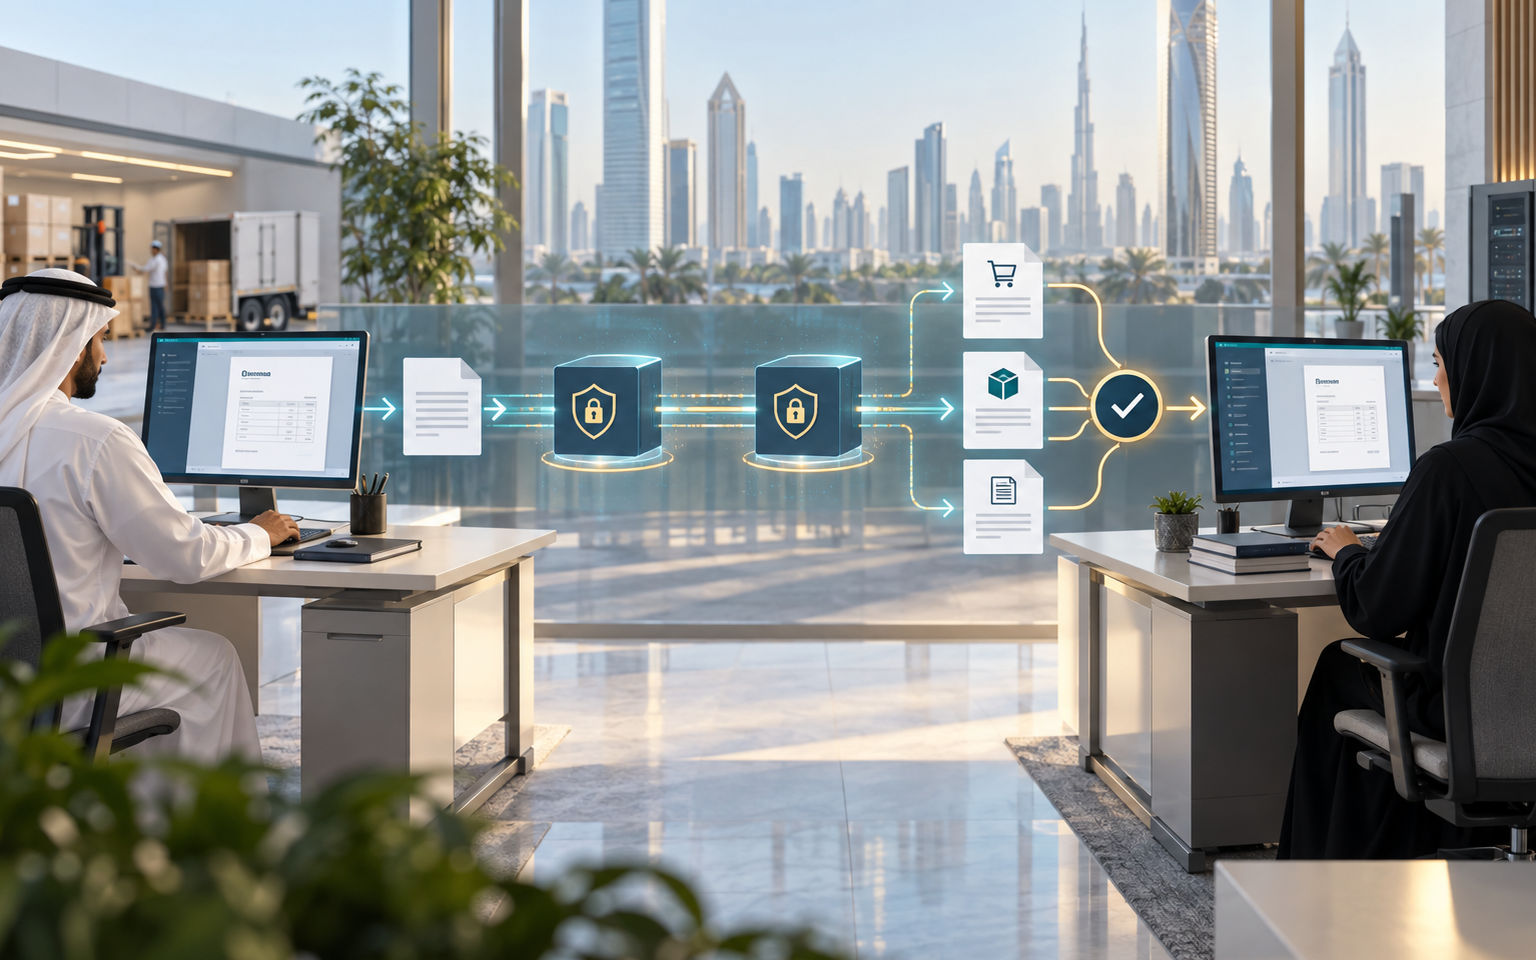
An electronic invoice under the UAE framework is more than an invoice created on a computer or a PDF sent by email. It is invoice data issued, transmitted, and received in a structured electronic format that systems can process automatically.
The UAE Electronic Invoicing Guidelines describe XML and UAE PINT-AE specifications within the Peppol framework. Required tax information is also reported through the framework to the Federal Tax Authority.
“A PDF is not automatically an e-invoice. The structured data and compliant exchange process are the important elements.”
2. When Does Mandatory Implementation Begin?
| Category | Current Timetable |
|---|---|
| Revenue of AED 50 million or more | Appoint ASP by 30 October 2026; implement by 1 January 2027 |
| Revenue below AED 50 million | Appoint ASP by 31 March 2027; implement by 1 July 2027 |
| In-scope government entities | Appoint ASP by 31 March 2027; implement by 1 October 2027 |
The pilot programme and voluntary implementation began on 1 July 2026. Organizations should continue checking official Ministry of Finance and Federal Tax Authority publications because requirements may be amended.
3. Who Is Affected?
The scope is broader than VAT-registered companies alone. Ministry of Finance guidance states that the framework applies to persons conducting business in the UAE in relation to business transactions, unless a stated exclusion applies. VAT registration status is not, by itself, the test for inclusion.
The framework covers B2B, B2G, G2B, and G2G transactions. Ordinary supplies to or from natural persons who are not conducting business, such as typical consumer transactions, are outside the currently stated scope. Specific exclusions and special cases still need to be assessed against the official rules.
4. How Does the UAE Model Work?
It would be misleading to describe the normal architecture simply as supplier to government portal to customer. The Ministry of Finance describes a decentralized model: supplier to supplier ASP, through the Peppol and UAE e-invoicing ecosystem, to the buyer ASP and then the buyer’s ERP or Accounts Payable environment.
At a simplified level, the supplier’s ASP validates invoice data, converts it to the required UAE-standard format where necessary, transmits the e-invoice to the buyer’s ASP, and reports required tax data. The buyer’s ASP validates and delivers the invoice to the buyer in an agreed format, while status and confirmation messages move through the system.
5. What Is an Accredited Service Provider?
An Accredited Service Provider, or ASP, is accredited within the UAE framework to facilitate compliant invoice exchange, validation, Peppol connectivity, and reporting of required tax information.
In-scope businesses must appoint an ASP and complete the required onboarding. The official guidance also addresses obtaining a Peppol participant identifier, agreeing how invoice data will be shared with the ASP, testing invoice exchange and tax reporting, and preparing systems and approval workflows for go-live. The Ministry of Finance maintains the official ASP list.
6. What Happens to the Supplier Portal?
Today, a supplier may log in to the customer’s Oracle, SAP, Ariba, Coupa, or another portal to submit an invoice. E-invoicing does not automatically eliminate that portal. The guidance recognizes that organizations may need to integrate applications with ASP systems and reconfigure approval workflows, but it does not prescribe one universal ERP or supplier-portal design.
| Operating Model | Practical Implication |
|---|---|
| Separate submissions | The supplier uses its ASP and also uploads to the buyer portal. This can create duplicate records, inconsistent data, reconciliation work, and duplicate-payment exposure. |
| ASP-to-ERP integration | Structured invoice data flows from the buyer ASP into ERP or AP. A separate manual invoice upload may not be necessary. |
| Portal remains in the process | The portal can remain a front end or collaboration channel if the overall design still satisfies issuance, exchange, validation, and reporting requirements. |
“The UAE authorities have not prescribed a universal one-submission or two-submission model for corporate supplier portals. The answer depends on system architecture and process design.”
7. Does E-Invoicing Replace Three-Way Matching?
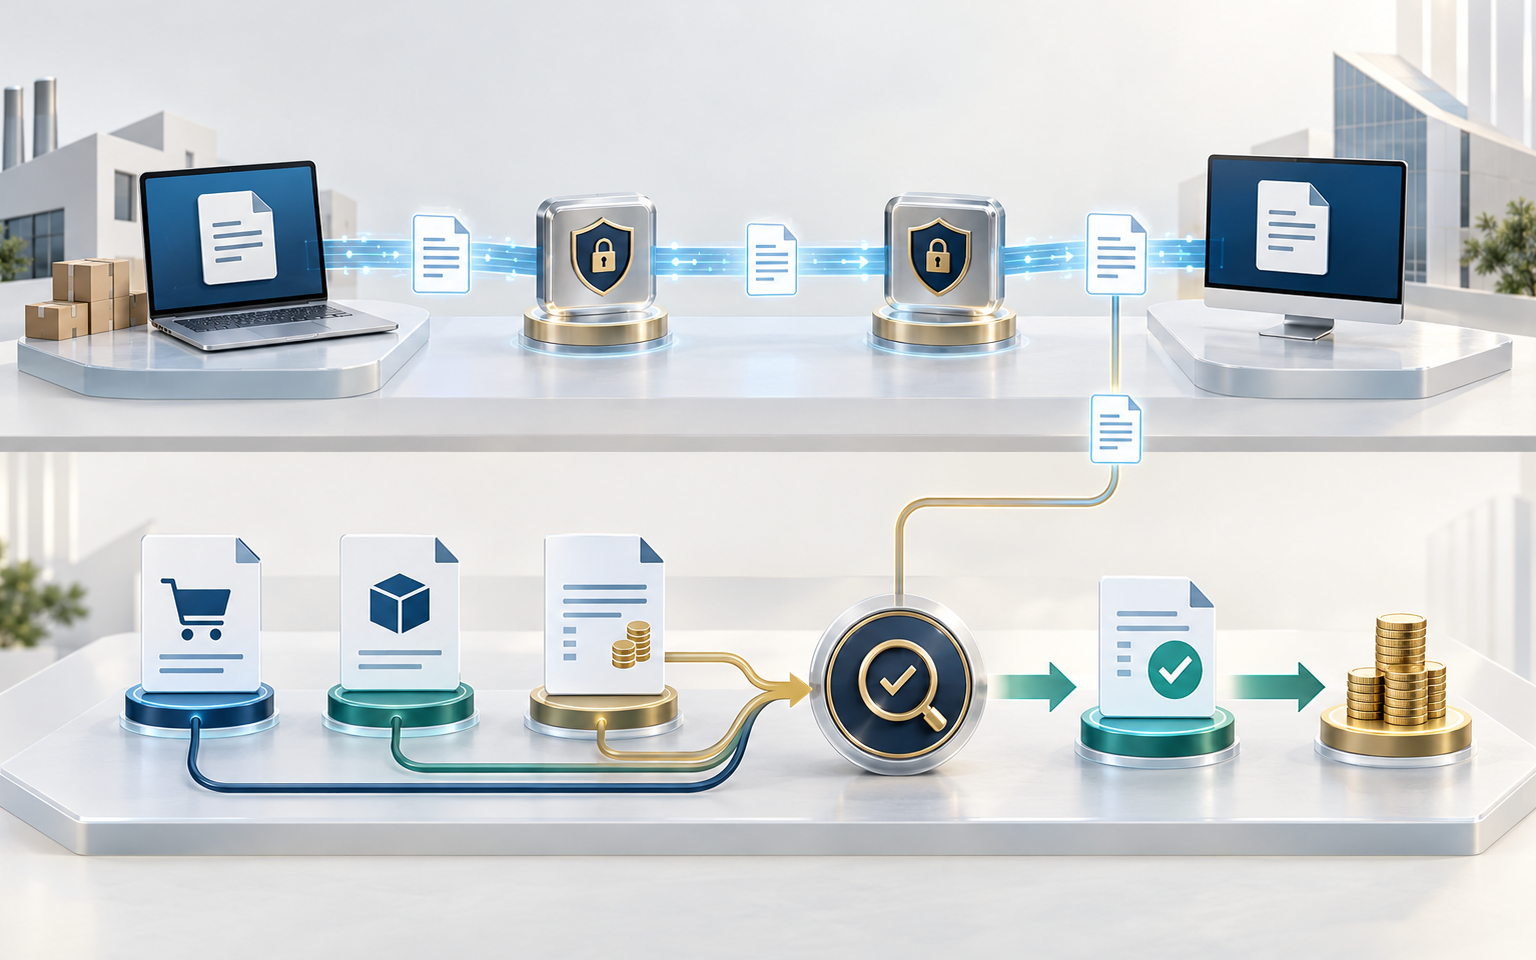
No. Three-way matching is an internal procurement and financial control. It compares the purchase order, goods receipt or service confirmation, and supplier invoice before payment approval. E-invoicing concerns the compliant issuance, exchange, receipt, and regulatory reporting of invoice information. These are different functions.
- The invoiced quantity exceeds the quantity received.
- The invoice price differs from the purchase order.
- The goods receipt or service confirmation is incomplete.
- A contractual requirement has not been satisfied.
- An internal approval remains outstanding.
“Successful regulatory transmission is not the same as authorization to pay.”
8. What Could This Mean for Procurement and AP?
- Supplier onboarding and the quality of legal, tax, and Peppol identification data.
- PO discipline, line-level references, units of measure, and master-data consistency.
- Clear supplier instructions on the ASP channel, existing portal, and transition arrangements.
- Updated contract clauses, PO invoicing instructions, and exception-management rules.
- A clear distinction between technical receipt, commercial rejection, and approval for payment.
- Controls for credit notes, retention, reconciliation, and duplicate-payment prevention.
9. Questions Organizations Should Ask Now
- Which implementation phase applies to each legal entity?
- Who will be appointed as the ASP, and how will it connect to ERP and procure-to-pay?
- Will suppliers still need to submit through the current portal?
- If two channels coexist, how will duplicate invoices and payments be prevented?
- How will PO, contract, and goods-receipt references be captured and validated?
- How will technical rejection differ from commercial rejection?
- What will be the authoritative invoice record, and how will it be retained?
- Who owns end-to-end readiness across Tax, Finance, AP, Procurement, supplier management, and IT?
10. The Bigger Picture
E-invoicing should not be viewed simply as replacing a PDF with an XML file. It introduces a new digital exchange layer connecting suppliers, service providers, buyers, ERP systems, and government reporting.
The opportunity is to integrate that layer into the existing process. The transition risk is to add e-invoicing on top of supplier portals without redesigning invoice receipt, leaving suppliers to enter essentially the same information through multiple channels.
The UAE framework does not remove three-way matching, procurement controls, or AP approval. It changes how compliant invoice information is created, exchanged, received, and reported.
Official Resources
- UAE Ministry of Finance — Electronic Invoicing Guidelines, 23 February 2026
- UAE Ministry of Finance — Accredited Service Providers
- UAE Ministry of Finance — Ministerial Decisions No. 243 and 244 of 2025 and implementation timetable
- UAE Ministry of Finance — May 2026 amendments
- Federal Tax Authority — UAE e-Invoicing
- OpenPeppol — UAE PINT-AE technical documentation
Important notice: This article is provided for general awareness and educational purposes only. It does not constitute tax, legal, regulatory, accounting, e-invoicing implementation, or compliance advice. Requirements may change and may apply differently depending on an organization’s circumstances. Businesses should verify current requirements directly with the UAE Ministry of Finance and Federal Tax Authority and obtain advice from appropriately qualified professionals and/or their Accredited Service Provider where required. Information reviewed: 24 September 2026. SANAD Consultancy Services (FZE) Support · Guide · Achieve